Joey O'Brien

Joey O'Brien

Principal Consultant · LSEG
  • DivisionQuant Services
  • DoctorateApplied Math, UL
  • FocusXVA · CCR · SS1/23
  • StackPython · C++ · R · ORE

Quantitative risk modelling, open-source pricing engines, and complex data.

I partner with investment banks, hedge funds, and risk technology teams at LSEG to validate counterparty credit risk and XVA models. Away from client engagements, I write practical notes on ORE workflows and publish research rooted in applied probability and network science.

Pillar I

Quant Finance & XVA

CVA, FVA, PFE, and SIMM validation built around reproducible challenger pricing.

Pillar II

Risk Engines & ORE

End-to-end risk engine implementation, vendor replacement, and production ORE migrations.

Pillar III

AI & Risk Workflows

Integrating agentic AI into risk workflows, alongside reproducible Python and R data pipelines.

Expertise

Quantitative Risk & Model Validation

Stage I · Calibration & Pricing

Curves, Derivatives & Market Data

Derivative PricingMulti-curve SOFR bootstrapping, swaps, caps, floors, swaptions, credit, and FX instruments.
Open Source Risk EngineXML market configuration, Python trade adaptors, and C++ QuantLib parity checks.
Discount & Fwd Spline
Stage II · Exposure & Valuation

Counterparty Credit & XVA Engine

XVA ModellingCVA, DVA, FVA, MVA, and KVA attribution alongside Jacobian par sensitivities.
Counterparty RiskMonte Carlo PFE profiles, ISDA SIMM initial margin, and CSA netting mechanics.
XVA Bridge
Stage III · Independent Challenge

Validation & Supervisory Governance

Model ValidationHistorical risk-factor backtesting, challenger prototypes, and stress testing.
Regulatory ComplianceAudit-ready documentation aligned with PRA SS1/23, FRTB, and Basel IV.
Traffic-Light Backtest

Recent Posts

Field Notes on Quantitative Risk, ORE & Data Science
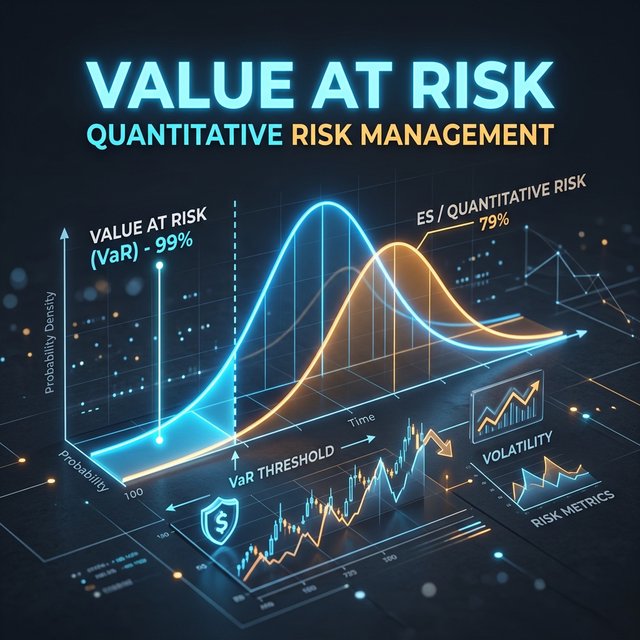
Featured · ORE Fundamentals ORE · Market Risk · 2026

Historical simulation VaR in ORE

How ORE’s historical simulation analytic turns a set of past market moves into VaR and expected shortfall. One window repriced by hand, checked against ORE, then sanity-checked and put in …
2026

Sensitivity Analysis in ORE

ORE · Sensitivities
Open-Source Packages & Data Pipelines Full portfolio

Media & Speaking

Podcasts, Keynotes, Industry Labs & Academic Seminars

FEATURED PODCAST LSEG Ahead of the Curve

Agentic AI in Quantitative Risk Management

Discussing the real-world operational transformation and governance challenges of deploying autonomous AI agents and Open Source Risk Engine (ORE) architectures on institutional trading and risk desks.

Key Discussion Topics:
  • Autonomous agents for model validation & stress testing
  • ORE architecture & multi-asset valuation workflows
  • Bank of England PRA SS1/23 supervisory alignment

Recent Summits, Keynotes & Appearances

Nov 2026 PANEL Frankfurt, Germany

Panel: Experiences with AI in the Context of QuantLib and ORE

Joined Luigi Ballabio (Co-Founder, QuantLib), Peter Caspers (Quantitative Dev Lead, LSEG), and moderator Roland Lichters (Co-Head of …

Nov 2026 PRESENTATION Frankfurt, Germany

ORE and Agentic AI: Opportunities to Build

Presented at LSEG’s 10-year anniversary event for the Open Source Risk Engine (ORE) in Frankfurt, exploring practical opportunities to build …

Jul 2026 PODCAST Online

LSEG Ahead of the Curve Podcast: Agentic AI in Quantitative Risk Management

Joined the latest episode of LSEG’s Ahead of the Curve podcast alongside Xabier Anduaga and Stuart Smith to discuss the real-world impact …

May 2026 PRESENTATION Paternoster Square, London, UK

LSEG’s Internal Adoption of ORE

Presented at the LSEG Quant Summit London 2026, discussing LSEG’s internal adoption, integration, and scaling of the Open-Source Risk Engine …

May 2026 PRESENTATION Paternoster Square, London, UK

ORE in the Era of Agentic AI

Presented at the LSEG Quant Summit London 2026, exploring the capabilities and limitations of Large Language Models (LLMs) in writing …

Nov 2025 PRESENTATION Tokyo, Japan

ORE & Risk Analytics Lab Tokyo

Attended and supported our APAC team’s ORE & Risk Analytics Lab event in Tokyo, which gathered Japanese market participants and risk …

News & Updates

  • November 2026 — ORE 10-Year Anniversary, Frankfurt: Spoke on ORE and Agentic AI: Opportunities to Build and joined Luigi Ballabio, Peter Caspers, and moderator Roland Lichters on the panel Experiences with AI in the Context of QuantLib and ORE. Event Info →
  • July 2026 — Podcast: Featured on LSEG’s Ahead of the Curve podcast discussing the real-world impact and future of Agentic AI in quantitative risk management. Listen & Watch →
  • November 2025 — Conference & Lab: Attended and supported our APAC team’s ORE & Risk Analytics Lab in Tokyo, presenting to risk professionals from leading financial institutions on CVA frameworks, custom risk models, and capital efficiency.
  • March 2021 — New Scientist & PLOS ONE: Our mathematical research on Fantasy Premier League published in PLOS ONE and featured in New Scientist: Maths reveals the top strategies to win at fantasy football. Read Paper (PLOS ONE) | arXiv